Market entry
You have a product and checkout, but need to identify the seller, payment recipient and first tax trigger.
BALANC.KZ · INTERNATIONAL TAX COMPLIANCE
Local support for foreign SaaS, subscription and electronic service providers. We assess Kazakhstan VAT obligations, prepare conditional registration, organise transaction data and manage the quarterly compliance workflow.
Built for international tax, finance and legal teams. Each engagement starts with an agreed scope and documented facts.
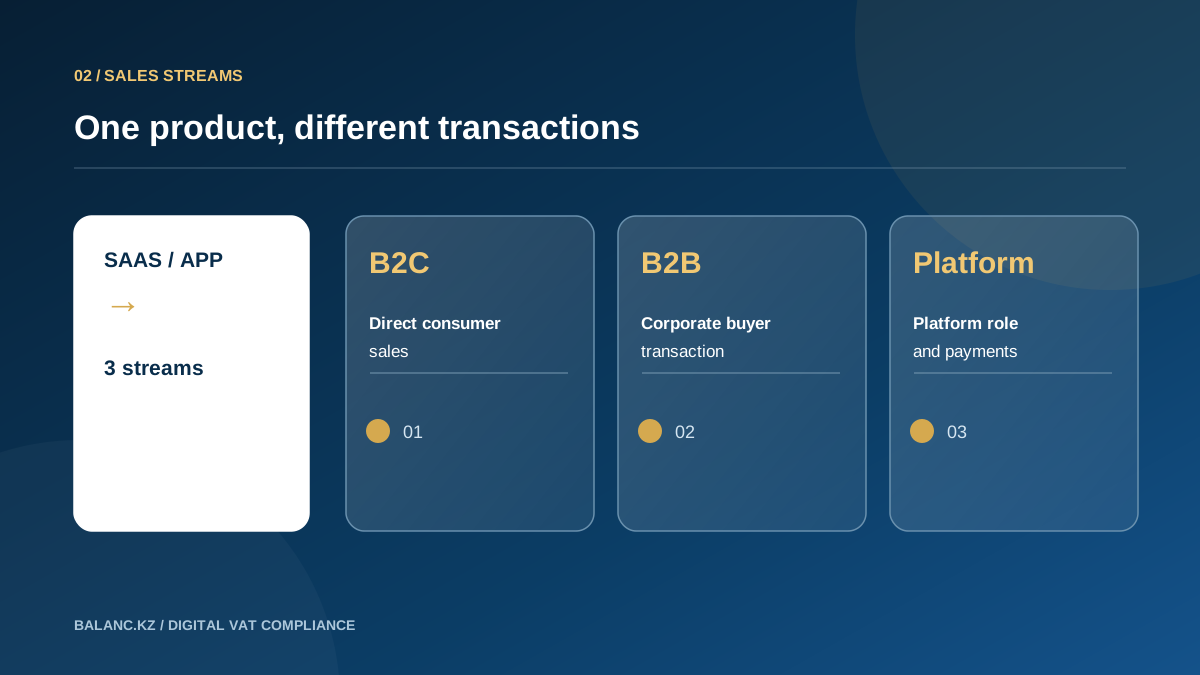
The same product may be sold to consumers, corporate buyers and through an intermediary. We separate those streams before registration or calculation.
WHO WE HELP
This practice supports a foreign legal entity supplying electronic services to customers in Kazakhstan through a website, app or platform. SaaS, cloud access and digital subscriptions require an assessment of the actual supply: a product's “digital” label alone does not decide its tax treatment.
You have a product and checkout, but need to identify the seller, payment recipient and first tax trigger.
Sales have started. You need a registration file, transaction register, calculation and payment controls.
Past quarters require a reconstruction of customer status, amounts, records and exposure.
SERVICES
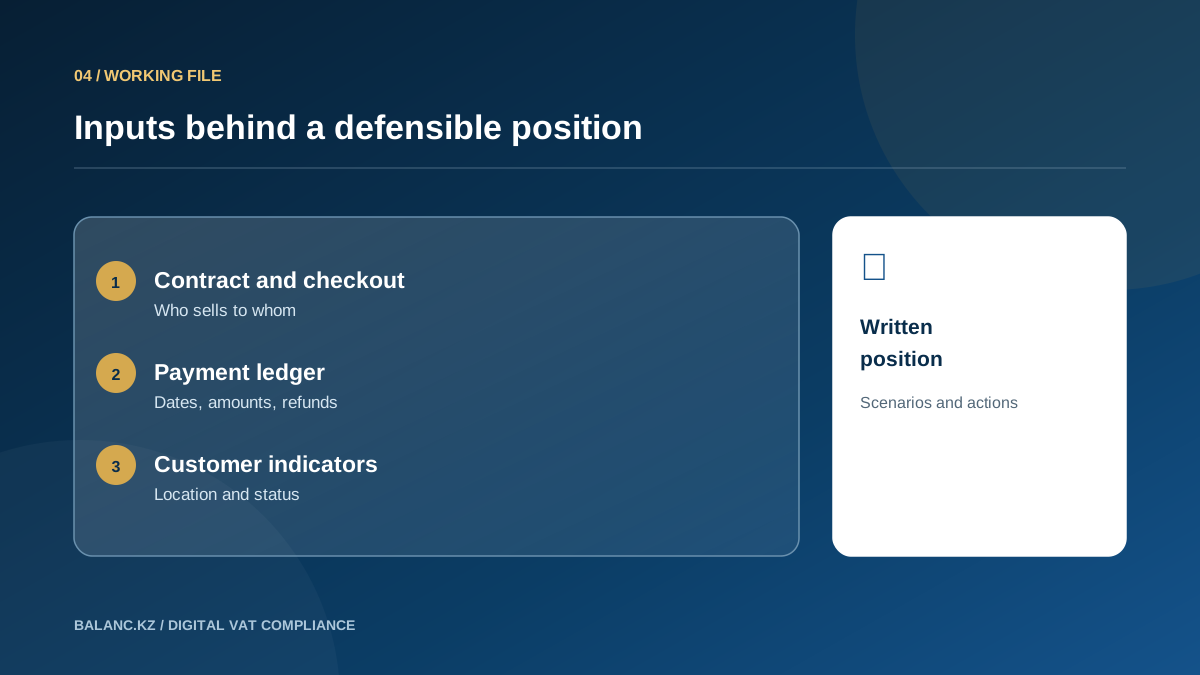
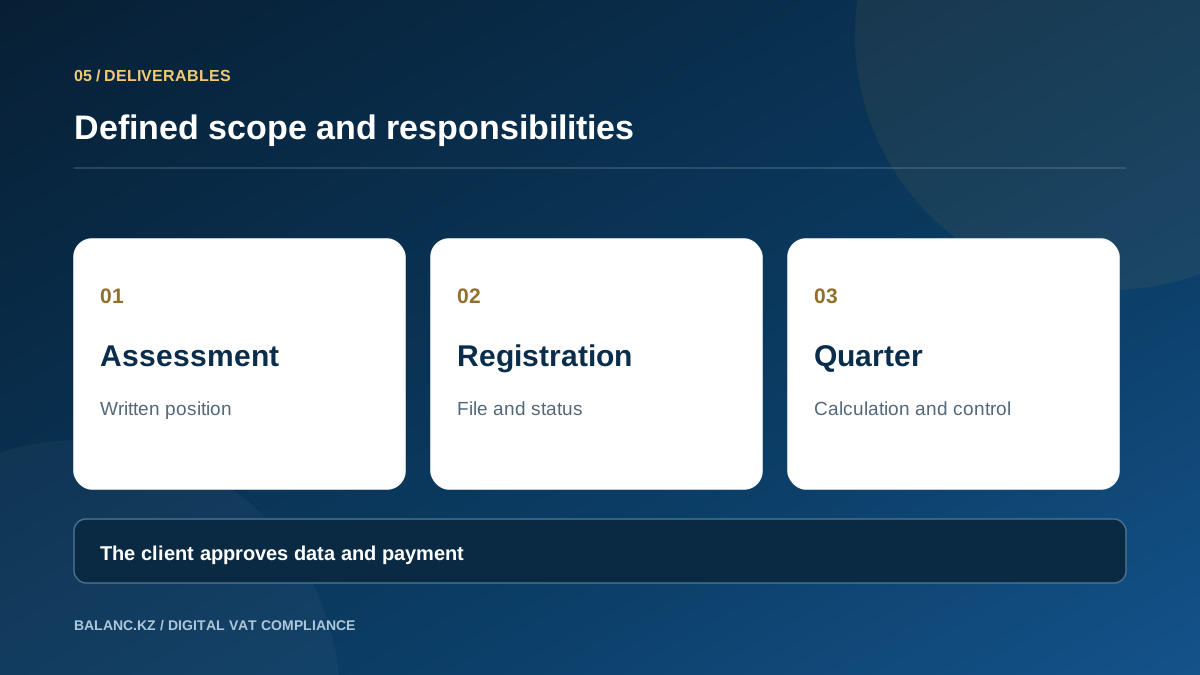
We review the product, contracts, buyer type, checkout, payment flow and Kazakhstan location indicators. You receive a short written position by scenario and an action list. This is a standalone engagement; registration is optional.
We review corporate documents and merchant identifiers, prepare the confirmation letter, support submission through the tax administration system and handle clarifications within our authority. Once assigned, we verify the BIN and register entry. Registration process and documents →
We specify order, payment, refund, customer location and intermediary fields. The output is an export specification and a tested transaction register; software development is separately scoped.
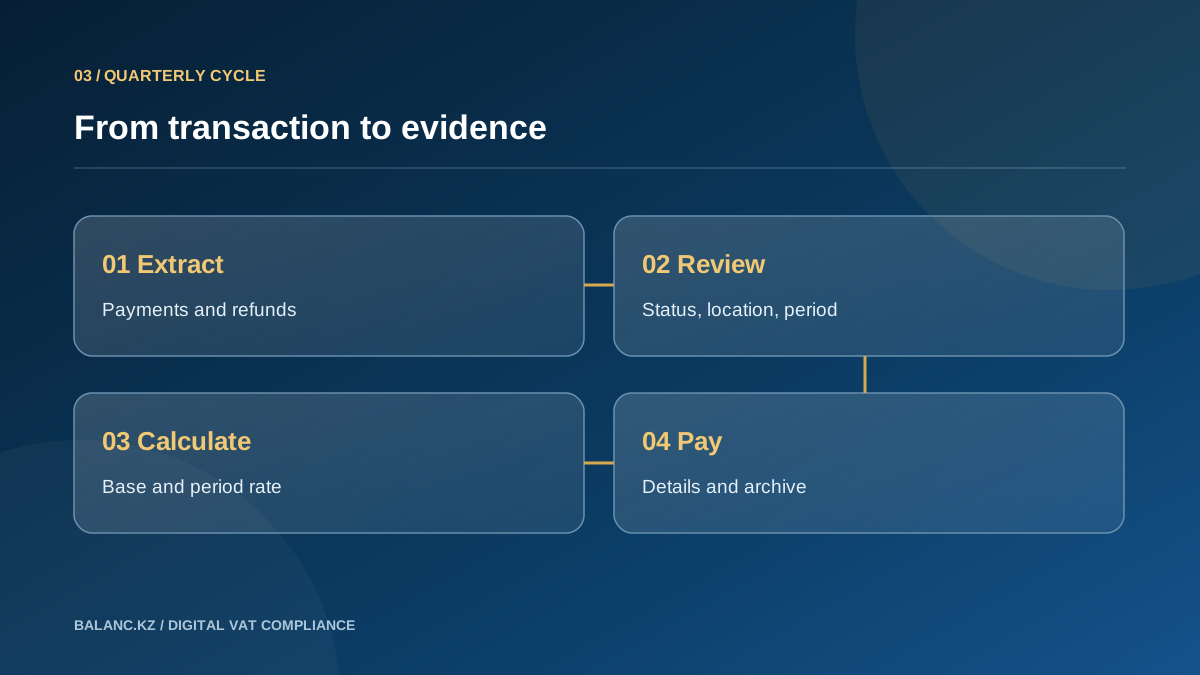
We reconcile consumer payments and refunds against payment provider reports, prepare the calculation, verify current payment details and retain supporting evidence. We coordinate with the tax authority under agreed powers.
We reconstruct payments and the applicable law for each historical period, estimate exposure and propose a sequence for correcting the position. Penalties, interest and an authority's decision cannot be promised in advance.
Separate engagements address marketplace or Merchant of Record roles, corporate buyers, official notices and evidentiary files. The conclusion follows the contract and actual flow, not the “agent” or “MoR” label.
LEGAL FRAMEWORK · 2026
The special regime in Chapter 95 of Kazakhstan's Tax Code covers electronic services supplied to individuals. Corporate sales require a separate analysis, including a possible non-resident services VAT mechanism for the Kazakhstan buyer.
The law uses residence, the payment bank or electronic money operator, IP address and telephone country code. One applicable Kazakhstan indicator can matter; conflicting evidence calls for a review of the underlying facts.
Finance Ministry Order No. 636 provides for a confirmation letter through the integrated tax administration system within one month of the customer's first payment, supporting documents and a register entry after BIN assignment.
The standard VAT rate for 2026 is 16%. Under the special regime, the turnover date is linked to the customer's payment and VAT is paid by quarter. Earlier years require their own applicable rules and rates.
This is an applicability overview. It does not classify every sale by a foreign company as a consumer supply or replace an analysis of goods, bundled offerings, intermediaries or a permanent establishment.
PROCESS AND DOCUMENTS
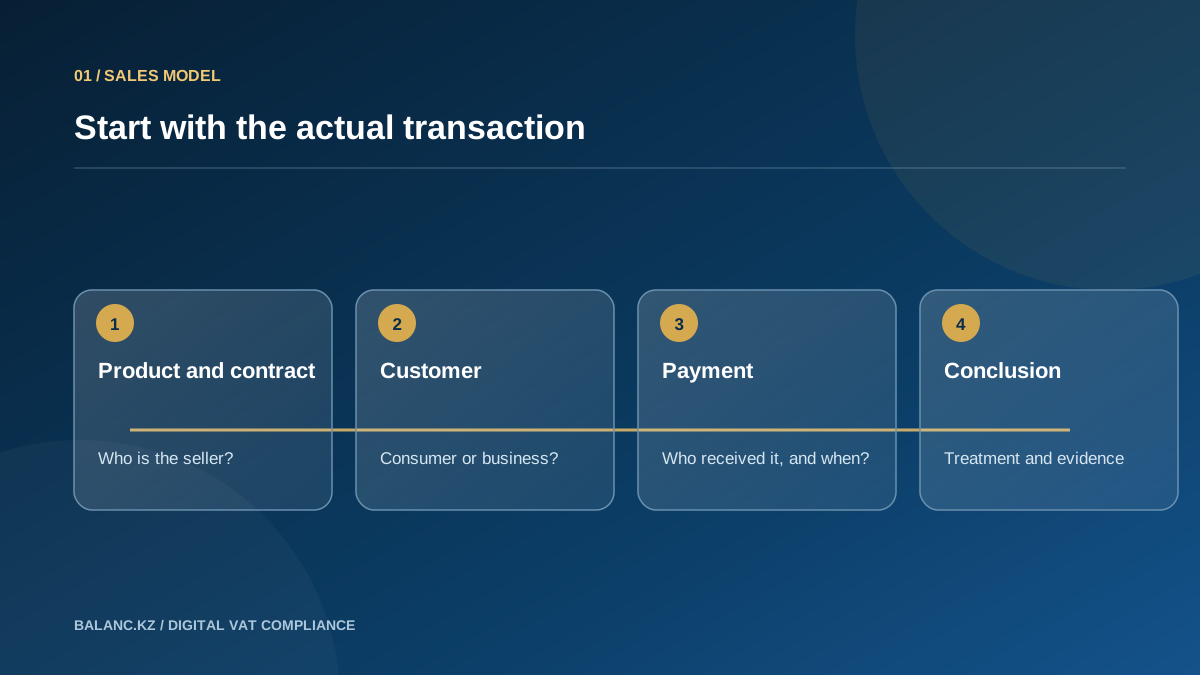
Identify the legal seller, incorporation country, product, B2C/B2B mix, first payment and sales intermediaries.
Review contracts, checkout and invoice samples, order and PSP exports, refunds, location indicators and earlier payments.
Set periods, sampling, responsibilities, deliverables, authority to act and an individual fee in writing.
Prepare documents, calculation and payment instructions; the client approves data and arranges payment; we reconcile the evidence.
A brief description is enough for the first enquiry. Do not submit buyer personal data, transaction files, contracts or digital signing keys through the public form. We agree a secure transfer channel after scoping.
ILLUSTRATIVE EXAMPLE
ABC Corp is fictional. It has direct consumer subscriptions, corporate licences and platform sales. We separate those three streams, record the first payment and platform documents, then determine the obligation and the data needed for calculation. Another company's contract may produce a different answer.
FREQUENT QUESTIONS
Conditional VAT registration is a separate procedure for a foreign company. A local entity or permanent establishment depends on the facts and may change the analysis.
Corporate sales do not automatically remove VAT. We examine buyer status, place of supply, contracts and any obligation of the Kazakhstan buyer to account for non-resident services VAT.
Yes. An assessment of applicability and the triggering date is a standalone written engagement based on agreed scenarios.
The legal obligation and payment details depend on the applicable rules and agreed arrangement. The company or an authorised payer arranges payment; our contracted work covers calculation and reconciliation.
We reconstruct payments and documents period by period, check the law then in force, estimate amounts and agree the steps for correcting the position and contacting the tax authority.
PRIMARY SOURCES
We establish the scope and tax position for each actual sales model.
START HERE
Share your legal entity and country, product, B2C/B2B mix, first payment date and the role of any platform or payment intermediary. We will identify the appropriate review and arrange a secure channel for documents.
Or email info@balanc.kz.